

How to Reduce Business Payment Fees: ACH, Card, Wire, and Check Compared
Cut what you spend on every payment and keep more cash in your business.

Key takeaways
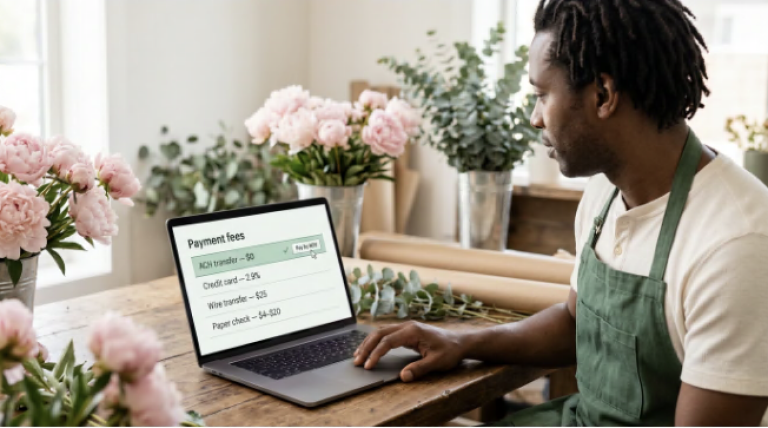
- ACH bank transfers are usually the cheapest way to pay vendors and a strong default for routine bills.
- Cards charge a percentage of each payment but can pay for themselves through float and rewards.
- Wires arrive fast for a higher flat fee, so save them for large or urgent payments.
- Paper checks look free but hide costs in materials, postage, staff time, and fraud risk.
If you’ve looked over your business books recently and noticed you’re paying a whole lot in payment fees, you might wonder how to reduce those fees and keep more of your hard-earned money. Today there are multiple payment methods for businesses, and tracking what each one costs for each transaction can seem complicated. That’s why we created this guide to reducing your business payment fees, covering everything you need to know to pay wisely.
What drives business payment fees?
Most fees come from the systems your money travels on, and US businesses rely on a mix of ACH, check, wire, and card payments. Cards carry an interchange fee, which is a small percentage of each charge. On top of that sit flat network fees and a markup your processor adds. So card costs climb as your invoices get bigger.
Checks and wires work differently. They charge per item, not per dollar. A wire has a set bank fee each time you send one. A check looks free but adds up through paper, postage, and staff time.
How much does each payment method cost?
Each method trades cost for speed, control, and rewards. Here is how the four common options compare in plain terms.
ACH transfer fees
ACH is a bank-to-bank transfer, and it is often the cheapest option. Many banks and tools charge a small flat fee or nothing at all. The cost stays the same whether you send $100 or $10,000. That makes ACH a strong default for routine vendor bills. See these ACH benefits for small business payments for more.
Credit card fees
Cards charge a percentage of each payment. Because it’s a percentage, the fee grows with the size of your invoice. But that fee buys real value for cash-flow-focused owners. You get float on your money and earn rewards on every dollar you spend.
Wire transfer fees
Wires move money fast, often same day, and they suit large or urgent payments. In exchange, banks charge a higher flat fee for each one. That flat fee hurts less on a big invoice than on a small one. Compare the tradeoffs in this guide to ACH vs. wire transfers.
Check costs
Checks feel free because there is no obvious per-payment charge. The real cost hides in checks, envelopes, stamps, and the hours your team spends creating and sending them. Paper checks also carry more fraud risk than electronic transfers like ACH.
Which payment method is cheapest for your business?
ACH is the cheapest payment method for most business bills, because it charges a small flat cost instead of a percentage. The right choice still depends on the invoice size, how fast the money must arrive, and what the vendor accepts.
Use this simple framework each time you pay.
- Invoice size: For large bills, ACH keeps a flat fee small while a card percentage adds up.
- Urgency: If the money must land today, a wire is worth its flat fee.
- Vendor acceptance: Some vendors refuse cards, so match the method to what they take.
For a deeper walk-through, see how to pick the right payment method for your business.
How to reduce fees on every payment method
Small routing choices add up to real savings over a year. Follow these steps to trim fees without slowing down payments.
- Default vendors to ACH. Make free or low-cost bank transfers your standard for routine bills.
- Negotiate your card processing rate. Ask your provider for a lower rate, especially as your volume grows.
- Reserve wires for urgent payments. Pay the higher flat fee only when speed truly matters.
- Replace checks with electronic transfers. Cut paper, postage, and staff time while lowering fraud risk.
- If you accept cards, set clear limits. Consider a card minimum or a surcharge where the law allows it.
When paying a higher fee is worth it
A higher fee is not always a loss. For cash-flow-focused owners, a card fee can pay for itself. Paying by card gives you float so you hold onto your cash for weeks longer. You also earn rewards on the spend, which offsets much of the fee.
Run the math on each payment. If the float and rewards beat the fee, the card wins. If not, route the bill to ACH instead.
Simplify business payments with Melio
Melio lets you pay every vendor from one place. Standard bank transfers with ACH are free, so routine bills cost you nothing to send.
You can also pay by card even when a vendor doesn’t accept cards. Your vendor simply receives a bank deposit, and they don’t need a Melio account. That keeps your float and rewards on the table without any extra steps for them.
Your payments sync with QuickBooks and Xero, so your books stay current. Ready to spend less on fees and keep more cash on hand? Sign up for Melio.
Reducing business payment fees FAQs
Find answers to the most frequently asked questions about reducing business payment fees below.
Is ACH always cheaper than a credit card?
Usually, yes, especially on larger invoices. ACH charges a small flat fee or nothing, while a card takes a percentage of each payment. But a card can still win when the float and rewards outweigh that fee.
Can a business pass credit card fees to customers?
In many cases, yes, through a surcharge on card payments. The rules vary by state and by card network, so check both before you start. You can also set a card minimum to keep small charges cost-effective.
What is the cheapest way to pay vendors?
For most routine bills, ACH is the cheapest way to pay vendors. The flat cost stays the same no matter how large the invoice. Reserve wires and cards for payments where speed or rewards justify the extra fee.
Are wire transfers worth the higher fee?
They can be when a payment is large or truly time-sensitive. A wire often lands the same day, which a standard ACH transfer cannot match. For everyday bills that are not urgent, ACH will almost always cost you less.
This content is for informational purposes only and should not be considered financial, legal, tax, or accounting advice. Melio does not provide professional advisory services. Always consult a qualified professional before making financial or business decisions.
Vendor Payment Automation: 5 Reasons To Make The Switch
Discover how automating supplier payments saves time, cuts errors, and improves your cash flow.
Supply Chain Technology: What It Is And How It Helps Your Business
Learn how supply chain technology helps your business move goods and money with less friction.
Negative Cash Flow: Causes And Recovery Strategies For Your Business
See why your business has negative cash flow and learn simple ways to recover and keep it running.
